
Ever had a rock fly up and crack your windshield? Or maybe your side window got smashed in a minor mishap? It happens. And when it does, your first thought might be, “How am I going to pay for this?” That’s where auto glass insurance claims come in. In a nutshell, if you have comprehensive coverage on your car insurance policy, there’s a good chance your auto glass repairs or replacements will be covered, making the whole process much less painful on your wallet.
So, let’s break down how this works without all the jargon and headache.
Understanding Your Coverage Options
Before you even think about filing a claim, it’s super important to know what kind of coverage you actually have. Not all insurance policies are created equal, especially when it comes to glass.
Comprehensive Coverage and Glass
This is your golden ticket. Comprehensive coverage is what typically pays for damage to your car that isn’t caused by a collision with another vehicle. Think things like theft, vandalism, fire, natural disasters (hail, falling trees), and yes – often, auto glass damage. If a rock hits your windshield, that usually falls under comprehensive.
It’s worth noting that some states (like Florida, Kentucky, and South Carolina) have specific laws that can affect glass deductibles under comprehensive policies, sometimes even waiving them entirely for windshield repairs or replacements. It’s always a good idea to check your state’s regulations and your specific policy.
Collision Coverage and Glass
While comprehensive handles most glass issues, collision coverage can come into play if the glass damage is part of a larger accident where your car hits another vehicle or an object. For example, if you rear-end someone and your windshield cracks from the impact, that would likely fall under collision. However, for standalone glass damage like a rock chip, collision coverage usually isn’t what you’re looking for.
Deductibles: What You Pay
Most insurance policies come with a deductible. This is the amount you have to pay out of pocket before your insurance kicks in. For example, if you have a $500 comprehensive deductible and your windshield replacement costs $600, you’d pay $500, and your insurer would pay the remaining $100.
Some policies, particularly in states with specific glass laws, offer what’s called “full glass coverage” or a “zero deductible for glass.” This means your deductible for glass repairs or replacements is $0. It’s a great perk, but it’s usually an add-on or a specific feature of certain policies, so don’t just assume you have it. Always check your policy documents or call your agent.
When to File vs. Pay Out-of-Pocket
This is a practical decision. If your deductible is high (say, $500) and the repair cost for a small chip is low (around $75-$150), it often makes more financial sense to just pay for the repair yourself. Filing a claim for a small amount might not be worth it, especially if it counts against your claim history, which could potentially lead to higher premiums down the road (though a single glass claim is usually less impactful than a collision claim). For a full windshield replacement, which can easily run $300-$1000+, using your insurance with comprehensive coverage usually makes sense, even with a deductible.
The Claim Process: Step-by-Step
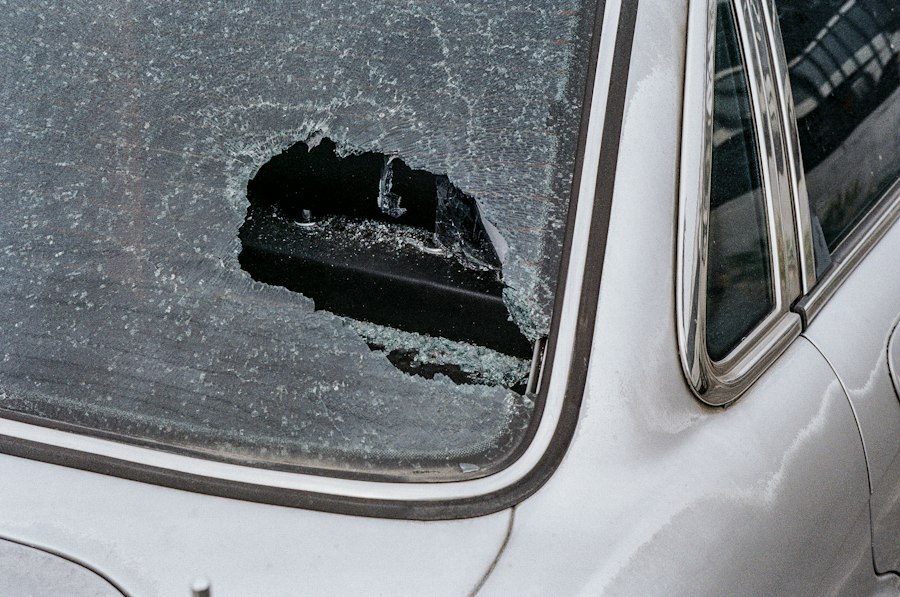
So, you’ve got glass damage and you’ve determined that filing a claim is the way to go. What now? The process is generally straightforward, but knowing the steps can save you some hassle.
1. Document the Damage
Before you do anything else, take photos or even a short video of the damage. Get clear shots of the crack or chip, including where it’s located on the glass. Also, take a few wider shots of your car to show the overall context. Note down the date and time the damage occurred, if you know it, and any relevant details (e.g., “rock hit windshield on Highway 101”). This documentation can be very helpful if there’s any dispute or questions from your insurer.
2. Contact Your Insurance Provider
This is the most crucial step. You can usually do this in a few ways:
- Call your agent directly: If you have a local agent, they can often guide you through the process, explain your coverage, and even help you initiate the claim.
- Call your insurer’s claims department: Most insurance companies have a dedicated 24/7 claims line. This is often the quickest way to get things moving.
- Use their online portal or app: Many insurers now offer online claim filing. This can be convenient, but make sure you provide all the necessary details.
When you contact them, be prepared to provide:
- Your policy number.
- The date and time of the incident.
- A description of the damage and how it happened.
- Your contact information.
They’ll open a claim and give you a claim number. Keep this number handy, as you’ll need it for all future communications.
3. Choosing a Repair Shop
This is where it can get a little interesting. Your insurance company will likely have a “preferred network” of auto glass shops. They might even try to steer you towards one of these. Here’s what you need to know:
- Your right to choose: In most states, you have the legal right to choose any qualified auto glass repair shop you want. You are not obligated to use a shop from your insurer’s preferred list.
- Preferred network benefits: Using a preferred shop can sometimes be smoother. They often have established billing relationships with your insurer, which might mean less paperwork for you. They’re also usually vetted by the insurance company for quality and pricing.
- Non-preferred shop considerations: If you choose a shop outside their network, make sure they are reputable, certified, and willing to work with your insurance company. You might need to pay the shop directly and then get reimbursed by your insurer, or the shop might handle the direct billing. Confirm this upfront.
- Mobile service: Many auto glass shops offer mobile service, where they come to your home or workplace to do the repair or replacement. This is incredibly convenient and often covered by insurance.
Once you choose a shop, let your insurance company know. They might want to contact the shop directly to confirm details and pricing.
4. Getting the Repair or Replacement Done
Schedule the appointment with your chosen shop. When you take your car in (or they come to you), they’ll assess the damage more thoroughly.
- Repair vs. Replace: For chips and small cracks (generally smaller than a dollar bill and not in your direct line of sight), a repair is often possible. This involves injecting a special resin into the damage, which prevents it from spreading and restores the structural integrity of the glass. Repairs are usually quicker, cheaper, and often have a lower (or even zero) deductible compared to replacements. For larger cracks, shattered glass, or damage that compromises visibility, a full replacement will be necessary.
- ADAS Calibration: If your car has Advanced Driver-Assistance Systems (ADAS), such as lane-keeping assist, adaptive cruise control, or automatic emergency braking, these systems often rely on cameras and sensors mounted to or integrated into your windshield. A windshield replacement will likely require recalibration of these systems to ensure they function correctly. This is a critical step for your safety and should always be performed by qualified technicians. Make sure the shop you choose has the equipment and expertise to do ADAS calibration if your vehicle requires it. Your insurance should cover this as part of the windshield replacement.
5. Payment and Deductible
After the work is done, the shop will handle the billing.
- If you have a deductible: You’ll pay your deductible amount directly to the shop. Your insurance company will then pay the remaining balance to the shop.
- If you have zero-deductible glass coverage: You shouldn’t owe anything to the shop for the glass work itself (unless there are additional services not covered by insurance).
- Direct billing vs. reimbursement: Most preferred shops will bill your insurance company directly. If you used an out-of-network shop, you might need to pay the full amount and then submit the receipt to your insurance company for reimbursement. Clarify this with both the shop and your insurer beforehand.
Once everything is paid and the repair is complete, your claim is usually closed.
Common Questions and Pitfalls
Even with a simple process, a few questions often pop up, and there are some things to watch out for.
Does a Glass Claim Raise My Premiums?
This is a big concern for many people. Generally, a single comprehensive claim for auto glass damage is less likely to significantly raise your premiums than a collision claim. Comprehensive claims are often viewed as “no-fault” incidents – things outside your control.
However, repeated comprehensive claims (e.g., several glass claims in a short period) could signal to your insurer that you’re a higher risk, which might lead to a premium increase. It also depends on your specific insurer, your claims history, and your state’s regulations. For a single rock chip, most people don’t see a major hike.
Repair vs. Replacement: What’s the Difference and Cost?
As mentioned, repairs are usually for small chips and cracks. They involve injecting resin to prevent spreading and restore integrity.
- Cost: Typically $75 – $150.
- Deductible: Often waived entirely by many insurers for repairs, even if you have a comprehensive deductible for replacements. This is because repairs are much cheaper than replacements, and it’s in the insurer’s best interest to fix a chip before it turns into a full crack.
- Time: Quick, usually 30 minutes or less.
Replacements are for larger cracks, shattered glass, or damage compromising visibility. The entire pane of glass is removed and a new one installed.
- Cost: Highly variable. A basic windshield for an older car might be $250-$400. A modern windshield with sensors for ADAS can easily be $600-$1000+, including calibration. Side and rear windows can also vary widely.
- Deductible: Your comprehensive deductible usually applies here.
- Time: Generally 1-3 hours, plus recommended “cure time” for adhesives before driving, especially for windshields.
It’s always better to get a chip repaired sooner rather than later. Temperature changes and vibrations can quickly turn a small chip into a large, unrepairable crack.
Aftermarket vs. OEM Glass
When your glass is replaced, you might be offered two types of glass:
- Original Equipment Manufacturer (OEM) glass: This is glass made by the same manufacturer who made the original glass for your car, often with the car manufacturer’s logo. It’s essentially identical to what your car came with from the factory.
- Aftermarket glass: This is glass manufactured by a different company to meet the same specifications and safety standards as OEM glass. It’s generally less expensive.
Your insurance company will often prefer to use aftermarket glass to save costs. However, in some cases, particularly for newer luxury vehicles or those with complex ADAS systems, using OEM glass might be recommended or even necessary to ensure proper functioning.
- Check your policy: Some policies specify that only OEM glass will be used for replacements. Others default to aftermarket.
- Your right to choose (again): You can often request OEM glass even if your insurer prefers aftermarket. You might have to pay the cost difference yourself, or your insurer might cover it if your policy allows for it or if the shop demonstrates a functional necessity. Discuss this with your insurer and the glass shop. It’s important to understand the potential impact, if any, on vehicle safety systems and warranties.
What if the Damage isn’t Covered?
If you only have liability insurance, your auto glass damage will not be covered by your policy. Liability coverage only pays for damage you cause to other vehicles or property. In this situation, you’ll be responsible for the full cost of repair or replacement out-of-pocket. This is a good reminder to regularly review your policy to ensure you have the coverage you need.
Proactive Steps and Prevention
While you can’t stop every rock from flying, there are some things you can do to minimize your risk of glass damage and make future claims smoother.
Regularly Inspect Your Glass
Take a few seconds periodically to look at your windshield, side, and rear windows for any small chips or cracks. Catching a chip early can save you a full windshield replacement down the line. A small chip is much easier and cheaper to repair.
Maintain a Safe Following Distance
This is a classic defensive driving tip, but it’s especially relevant for preventing rock chips. The further you are from the vehicle in front of you, the less likely you are to get hit by debris they kick up. Pay particular attention on highways, construction zones, or roads with gravel.
Park Smart
When parking, consider where you are. Avoid parking under trees that might drop branches or sap (which can damage wipers and glass sealant). In areas prone to hail, try to find covered parking. While not always possible, being mindful of your parking environment can help.
Review Your Policy Annually
Don’t just set it and forget it. Every year, when your policy renews, take a few minutes to review your coverage. Check your deductibles, understand your glass coverage specifics (e.g., zero-deductible options, OEM vs. aftermarket), and confirm that your contact information is up to date. If you’ve bought a new car with ADAS features, make sure your policy reflects this and covers necessary recalibrations. If you have questions, call your agent or insurer – that’s what they’re there for.
Final Thoughts
| Metric | Description | Typical Value | Notes |
|---|---|---|---|
| Claim Filing Time | Average time to file an auto glass insurance claim after damage | Within 24-48 hours | Filing promptly helps speed up the process |
| Deductible Amount | Out-of-pocket cost before insurance covers the repair | 0 – 500 | Varies by policy; some policies waive deductible for glass claims |
| Claim Approval Rate | Percentage of auto glass claims approved by insurers | 85% – 95% | Depends on policy terms and claim validity |
| Repair vs Replacement | Percentage of claims resulting in repair vs full replacement | Repair: 60% | Replacement: 40% | Repair preferred when damage is minor |
| Average Repair Time | Time taken to complete glass repair or replacement | 1 – 3 hours | Depends on damage severity and service provider |
| Coverage Types | Types of coverage applicable to auto glass claims | Comprehensive, Full Glass Coverage | Comprehensive usually covers glass damage |
| Impact on Premium | Effect of filing a glass claim on insurance premium | Minimal to None | Many insurers do not increase premium for glass claims |
Dealing with auto glass damage isn’t fun, but understanding your insurance coverage and the claims process can make it a lot less stressful. Remember, the key takeaways are to know your coverage (especially comprehensive and your deductible), document the damage, contact your insurer promptly, and don’t be afraid to ask questions about repair options or shop choices. With a little preparation, you can get your car’s glass fixed and get back on the road safely without too much fuss.